Social Security Medicare
Don't Lock Young Americans Into Social Security
COMMENTARY
Published July 7, 2026 • Read time: 4m
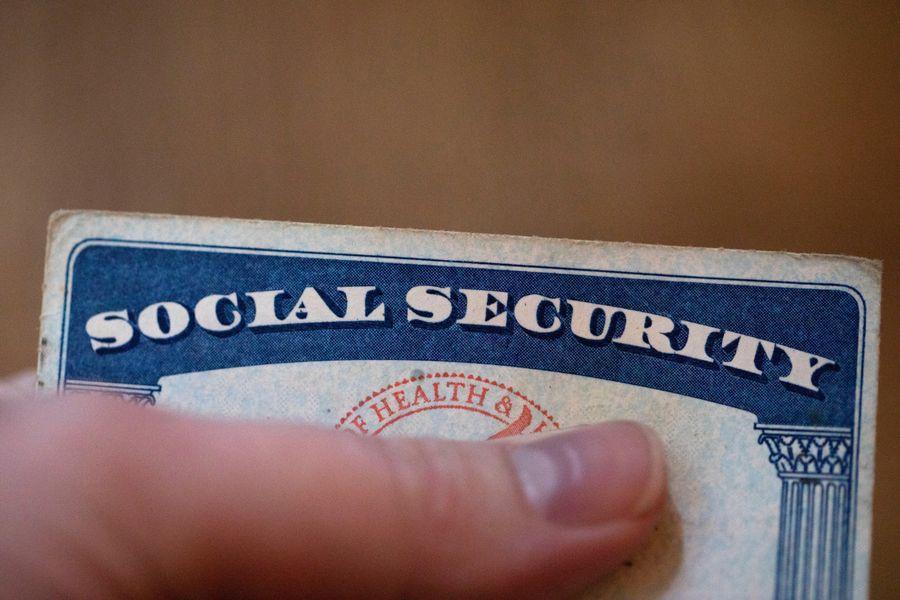
The Social Security trust fund is projected to run out of money by 2032. Without legislative reforms, retirement benefits for tens of millions of Americans could face significant cuts.
As lawmakers debate how to preserve the program, most proposals focus on raising payroll tax revenue or making other budgetary adjustments. But these discussions miss a larger point: The program itself is increasingly ill-suited for younger generations. Rather than forcing Americans into a system that may not deliver on its promises, policymakers should allow young workers to opt out and prepare for retirement in their own way.
America’s younger generations are coming of age amid an affordability crisis. Housing costs, groceries, health insurance, transportation, and higher education consume a growing share of household budgets. In such an environment, financial flexibility matters more than ever.
Yet every paycheck is hit by a 6.2% Social Security payroll tax, withheld with the promise that workers will receive benefits decades later when they reach retirement age. For many millennials and members of Generation Z, that promise appears increasingly uncertain.
The idea that workers simply “pay in” and later receive back what they contributed has long been misleading. Today’s payroll taxes largely fund benefits for today’s retirees. As demographic pressures strain the system, younger Americans face the prospect of paying into Social Security for decades while receiving far less in benefits than previous generations. In turn, few Gen Zers count on Social Security to support them in retirement someday. More than half expect to rely on personal retirement accounts as their primary source of income in retirement. Only 35% expect the program to still be around when they retire.
Rather than dragging younger workers through years of uncertain taxation, policymakers should give them a choice. Americans who are decades away from retirement should be allowed to opt out of Social Security and pursue retirement planning through private alternatives.
The freedom to decide how to spend and save one’s income is deeply ingrained in American culture. Some people rent apartments, rely on public transportation, and prioritize international travel. Others buy homes, raise families, and invest heavily in property or small businesses. The diversity of lifestyles that defines the United States is made possible by economic liberty.
Social Security’s mandatory payroll tax limits that liberty, particularly for younger generations who are unlikely to receive the same value from the program as their parents and grandparents. Every dollar directed to Social Security is a dollar that cannot be used to pay down debt, purchase a home, invest in education, build a business, or save independently for retirement.
Private retirement accounts also offer greater opportunities for long-term growth. Historically, diversified investments held through 401(k)s, IRAs, and other retirement vehicles have generated substantially higher returns than the growth reflected in Social Security benefits. 401(k) plans return 5-8% annually, while Roth IRAs can reach 7-10%. In contrast, Social Security payments reflect 1-3% annual growth, matching cost-of-living adjustment inflation rates.
Younger workers, with decades of investing ahead of them, are uniquely positioned to benefit from compound growth. But the ineffective Social Security system holds them back from the thousands to millions in returns available by private sector investment vehicles.
In an era of accessible investing platforms and unprecedented financial tools, a one-size-fits-all government retirement system makes less sense than ever. Americans are capable of making different choices about their financial futures. They should have the freedom to decide whether Social Security is one of them.
As lawmakers confront Social Security’s looming insolvency, they should look beyond tax increases and accounting fixes. The debate should include a more fundamental question: Why should younger Americans be required to participate in a system they increasingly doubt will deliver on its promises?
Social Security was created for a different era, when workers had fewer options, people did not live as long, and America’s population was booming. Those conditions no longer exist, and it leaves the system unable to afford its original obligations.
If Social Security cannot provide future generations with the same security it once promised, then those generations should be free to pursue their own path. Young Americans deserve the freedom to build their own financial future.
Support Our Mission
The Internet provides an endless stream of content. Not all of it is worth your time. That's why, every day, RealClearPolitics curates the most essential news and information—from all sides and across mediums. The links, videos, and podcasts curated here are the product of human judgment, not algorithms or AI. Please help power our mission of presenting a thoughtful, balanced public discourse through a tax-deductible donation.
Would you consider supporting us today?
Contributing to RealClear Politics through the RealClear Media Foundation supports essential initiatives that drive meaningful change.
RCP Today
Top stories on RealClearPolitics
The Takeaway
Polling intelligence and analysis delivered to your inbox
World News
Featuring the latest world news
Policy
Featuring the latest policy news
Support Our Mission
As part of RealClearPolitics, authors aim to provide balanced, non-partisan analysis by presenting top reporting and commentary from all sides of the political spectrum.
Trusted by policymakers and citizens alike since 2000